Research update · 8 October 2026 · ASX: MRD · OTC: MRDMF
Why Selectro's 91.8% result matters
Mount Ridley's 91.8% scandium leach recovery is encouraging, particularly because Selectro™ achieved it at low temperature and atmospheric pressure on unbeneficiated Grass Patch material. The bigger investment question is whether that chemistry can become a commercially viable Western processing route for scandium and heavy rare earths.
The comparison with Sunrise Energy Metals (ASX: SRL) helps explain both the opportunity and the development gap. Syerston has higher-grade feed, a feasibility-study flowsheet and a conditional US$400m US loan commitment. MRD has promising results on one laboratory composite, not a proven plant or qualified product. A higher bench leach percentage does not by itself establish better commercial recovery or economics.
Meanwhile, Phase 2 re-assays have found scandium up to 8km beyond Grass Patch's current resource boundaries. That strengthens the case for further resource modelling, but it does not add tonnes to the existing estimate yet. Our focus is what these developments could change, what remains unproven, and why processing capability matters alongside the deposit itself.
Commissioned and paid for by Mount Ridley Mines Limited. Company figures and test results below come from the 8 October Cashu Research update; external policy and peer sources are linked separately.
At a glance
- 91.8% scandium leach recovery in Selectro Test 3.
- 84% average heavy rare earth recovery at approximately half the earlier reagent dose.
- Up to 8km beyond the current resource boundaries in Phase 2 re-assays; not yet included in the Mineral Resource.
- US$400m conditional backing for SRL, not MRD; financial close remains subject to conditions.
- Speculative Buy reiterated; A$0.144 price target maintained.
Development caveat: These are not commercial production results. The price target is not a guaranteed return.
Selectro versus SRL and other processing routes
The most useful comparison has two dimensions: the intensity of the extraction route and how far it has progressed toward saleable product. A high laboratory recovery is encouraging, but it is not a substitute for engineering, downstream purification, customer qualification or financing.
| Route | Feed and operating conditions | Reported recovery or output basis | Evidence and qualification |
|---|---|---|---|
| MRD Grass Patch, Selectro Test 3 | Approximately 50ppm Sc, unbeneficiated composite; low temperature, atmospheric pressure; maximum recoveries reached in under four hours. | 91.8% scandium leach recovery; 84% average HREE. | Initial laboratory work on one eight-sample composite. Not recovery to saleable oxide, not pilot operation. |
| Sunrise Energy Metals (ASX: SRL), Syerston | HPAL: high-pressure sulphuric-acid leaching in autoclaves; about 250°C. Average life-of-mine feed grade 656ppm Sc. | 88% processing-recovery assumption in the March 2026 feasibility study. | A developed project flowsheet and study basis, not the same measurement as MRD's bench leach. The feed is much higher grade. [2] |
| Scandium International (SCY), Nyngan HPAL | Laterite feed; sulphuric-acid pressure leach followed by solvent extraction; approximately 409ppm Sc in the cited study basis. | 70–80% overall recovery range quoted in the supplied Cashu update. | Different recovery boundary and feed mineralogy. The company's project materials describe a permitted feasibility-stage development, not an operating mine. [1], [3] |
| Nyngan acid-bake alternative | Atmospheric sulphuric-acid bake and water leach; heated rather than ambient. | Approximately 75% recovery quoted in the Cashu update. | An alternative testwork route, not a separate producing plant or an equivalent commercial benchmark. [1] |
| Red-mud extraction studies | Alumina-refinery residues; selected strong-acid, heated laboratory routes. | 90–95% in the selected academic bench studies cited by the Cashu update. | Feed chemistry, impurities and downstream costs vary. This range is not a general industry performance standard. [1] |
| Rio Tinto, Sorel-Tracy, Canada | Scandium recovery from titanium-dioxide production waste streams. | First high-purity oxide batch in May 2022; 3t/year nameplate capacity stated at launch. | A commercial-scale demonstration reference for an allied by-product route. No like-for-like recovery percentage used here; the 2022 capacity is not a claim about current output. [4] |
On a phone, swipe within the comparison table to see each column. The table does not rank these routes by recovery.
Read the comparison as route context, not a recovery league table. MRD's 91.8%, Syerston's 88% and Nyngan's quoted overall range have different feed grades, mineralogy, process boundaries and evidence maturity. They cannot establish which route has the best unit costs, lowest capital intensity or highest recovery to a qualified product.
The cleaner experiment is within Grass Patch itself: the supplied update reports 27.6% scandium recovery from the conventional HCl baseline on the same T3803 composite, versus 91.8% in Selectro Test 3. Selectro's three bench tests moved from 62.1% to 80.0% to 91.8%. That supports further testwork, not a bankable plant design.
What could make Selectro different
If low-temperature, atmospheric extraction survives scale-up, it could avoid the autoclaves and operating severity associated with HPAL. Recovering scandium and heavy rare earths in one leach could also broaden the potential value of the feed. These are potential advantages, not demonstrated savings.
The reagent chemistry is proprietary and undisclosed. The update describes recyclable, closed-loop chemistry, but commercial reagent recycling, consumption, impurity rejection, residue treatment and costs remain to be established. Lower temperature alone does not prove lower whole-of-process cost.
There is also a metal trade-off: gallium recovery fell to 41.5% at the lower reagent dose, compared with 55.8% in Test 2. A process has to optimise the value and quality of all saleable products, not only maximise one recovery number.
SRL is therefore both a comparator and a reminder of the development gap. Syerston brings higher-grade feed, a feasibility study and conditional strategic financing. MRD brings early testwork that could open a different processing route. They are not at the same stage.
Recent macro events: processing is now strategic infrastructure
- April 2025 controls still matter. China introduced export licensing for seven elements including scandium, dysprosium, terbium and yttrium. S&P Global's 24 September 2026 reporting distinguishes these restrictions from the later controls suspended under the trade truce. A temporary easing of trade tensions is not the removal of the original licensing regime. [5]
- 7 August 2026: US financing moves into scandium. The US Office of Strategic Capital announced a conditional US$400m loan commitment to Sunrise. Its stated objective extends beyond a mine to a Western-aligned scandium value chain, including metallisation and additive manufacturing. Financial close still requires legal, financial and technical conditions to be satisfied. It is not funding awarded to MRD. [6]
- 24 September 2026: a short truce, not a permanent solution. CNBC reported US Treasury Secretary Scott Bessent's announcement of a two-month extension to 10 January 2027. Continued licensing uncertainty leaves manufacturers exposed even if trade flows improve. [7]
- 2 October 2026: SRL proposes a US parent and Nasdaq listing. Reuters reported the proposed redomiciliation, aligned with the conditional US financing. Sunrise said its underlying assets and projects would not change. This is a proposed corporate transaction, not evidence that the processing plant has been completed. [8]
Australia's Critical Minerals Production Tax Incentive provides the domestic policy context: a refundable 10% offset on eligible Australian processing expenditure from 1 July 2027 to 30 June 2040, for up to ten years per registered activity. It excludes mining, beneficiation and capital expenditure. MRD's eligibility, registration and benefit are not assured. The distinction matters because governments are supporting the transformation of feedstock, not simply ownership of a resource. [9]
Why Western processing capability matters
Western manufacturers do not just need another scandium deposit. They need a dependable way to turn it into usable material without relying on Chinese separation and refining. A trade truce can ease the immediate pressure, but it does not create a new processing plant or remove the need for export licences.
An Australian mine can still leave an allied customer dependent on another jurisdiction if its material must travel there for separation, refining or metallisation. The supply chain is only diversified when the necessary processing stages, know-how and qualified output can also be delivered.
Scandium oxide supports solid oxide fuel cells, and scandium can improve aluminium alloys used in aerospace, defence and additive manufacturing. Heavy rare earths such as dysprosium and terbium sit in a different chain, notably permanent magnets. Selectro's multi-element results are relevant to both conversations, but MRD has not demonstrated a finished alloy, fuel-cell input or magnet product.
For Western customers, the relevant tests include reliable access, repeatable purity, qualification, delivered cost and sufficient volume. For MRD, an Australian-owned process could become strategically valuable if it works across suitable feeds and supports those requirements. It is not enough for the IP owner to be Australian: downstream capability, reagent supply, equipment, finance and offtake also have to be secure.
The resource update strengthens the feedstock story
Phase 2 re-assays reported on 23 September found scandium up to 8km beyond the current resource boundaries. Highlights in the supplied update include 40m at 102.1ppm Sc₂O₃ from 18m in MRAC1040 and 22m at 119.4ppm Sc₂O₃ from 12m in MRAC1036. Another 2,800 Phase 3 pulps reached the laboratory on 21 September.
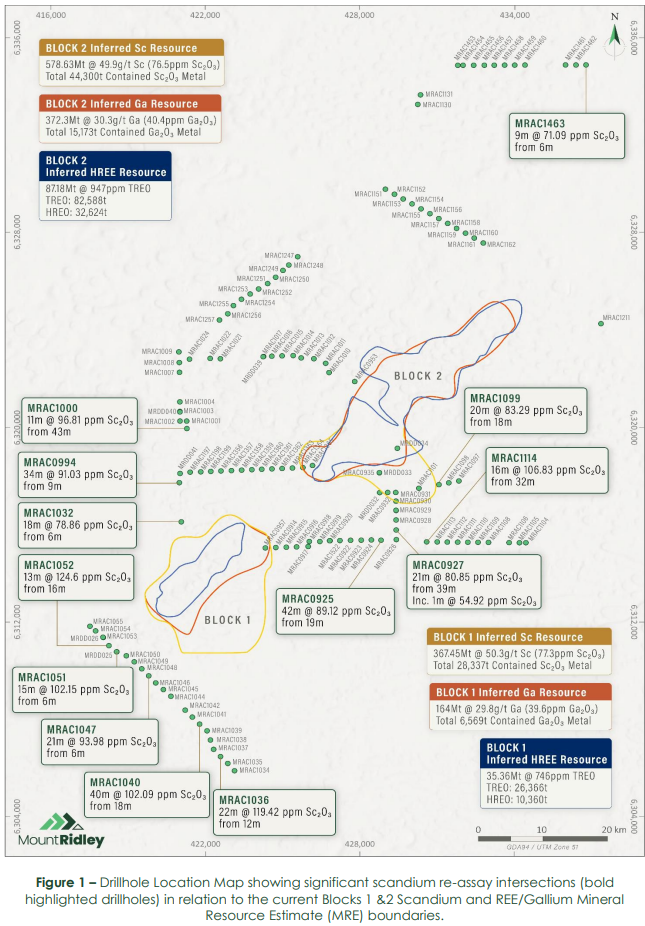
These are exploration results outside the current estimate, not additional tonnes already included in it. The current Inferred Mineral Resource remains 946Mt at 50.1ppm scandium, containing 47,357t of scandium metal. Intercepts reported as Sc₂O₃ must not be directly compared with metal grades without conversion: Sc₂O₃ = Sc × 1.534.
The update maintains the A$0.144 target, using A$4,000 per tonne of contained scandium and assigning zero value to Selectro licensing. The A$0.039 last-close reference and A$54.4m market capitalisation are snapshots at 7 October 2026, not live quotes. The roughly 269% target-implied upside is speculative, not a forecast. Any higher target depends on an updated resource; re-assays alone do not change it.
What would turn the processing option into a business?
- 01 · Third-party feed: publish results on suitable material beyond the single Grass Patch composite.
- 02 · Scale: reproduce results on beneficiated bulk feed and at pilot scale with a complete mass balance.
- 03 · Saleable product: demonstrate separation, impurity control, purity, overall recovery and customer qualification.
- 04 · Defensible economics and IP: quantify reagents, recycling, energy, waste and capital requirements; establish a workable patent or confidential licensing structure.
- 05 · Commercial adoption: secure funded development, partnerships or licence terms that can be tested against customer needs.
Until those steps are evidenced, licensing remains an option rather than revenue, and support for allied processing is not a guarantee of support for MRD. Further funding and dilution may be required. A more durable trade settlement could also reduce near-term policy urgency without resolving the longer-term concentration problem.
Sources and related research
- Cashu Research, Mount Ridley Mines update, 8 October 2026, pp. 1–4. Original report available through the PDF download on this page. MRD company results and the Nyngan/red-mud comparison ranges above are attributed to this supplied note.
- Sunrise Energy Metals, quarterly activities report dated 21 April 2026, including the March 2026 feasibility-study design parameters: https://api.investi.com.au/api/announcements/srl/fde08495-f5f.pdf
- Scandium International, Nyngan project overview: https://scandiummining.com/projects/nyngan-scandium-project/
- Rio Tinto, first North American scandium oxide production, 6 May 2022: https://www.riotinto.com/en/news/releases/2022/rio-tinto-becomes-the-first-producer-of-scandium-oxide-in-north-america
- S&P Global, export-control backdrop, 24 September 2026: https://www.spglobal.com/energy/en/news-research/latest-news/metals/092426-trump-and-xi-to-discuss-chinas-rare-earth-export-controls
- US Office of Strategic Capital, conditional Sunrise loan commitment, 7 August 2026: https://www.war.gov/News/Releases/Release/Article/4566598/office-of-strategic-capital-signs-400-million-conditional-loan-commitment-with
- CNBC, US–China truce extension, 24 September 2026: https://www.cnbc.com/2026/09/24/us-china-trade-truce-bessent-trump-xi.html
- Reuters via MINING.COM, Sunrise's proposed US redomiciliation, 2 October 2026: https://www.mining.com/web/sunrise-energy-metals-plans-us-redomicile-primary-nasdaq-listing
- Australian Government, Critical Minerals Production Tax Incentive: https://www.industry.gov.au/mining-oil-and-gas/minerals/critical-minerals/critical-minerals-production-tax-incentive
Related note: Selectro Test 3, 17 September 2026
DisclosureThis update was commissioned and paid for by Mount Ridley Mines Limited. Cashu Research or Cashu Group has received fees for research or corporate communication services from companies mentioned, and its directors, employees or associates may hold or trade those securities. This is general research, not personal investment advice. All current resources are Inferred; Selectro is laboratory-scale and its chemistry undisclosed. Peer figures are included for context, not investment recommendations on those companies. Read the original four-page PDF and its complete disclosures before relying on the figures.
This research is general advice only and does not take into account your objectives, financial situation or needs. Cashu Technologies Pty Ltd is a Corporate Authorised Representative (AR No. 001318029) of Adviser Solutions Group Pty Ltd (AFSL 485946).