Cashu Ideas · Undervalued Companies · 5 November 2026
Unpaid research. Cashu holds no shares in Euroseas Ltd.
This is general investment commentary, not personalised financial advice. Cashu is not regulated in North America. The BUY rating and price target are the report's investment view and model output, not a guaranteed return.
Euroseas Ltd. (NASDAQ: ESEA) owns feeder and intermediate containerships. In this edition of Cashu's Undervalued Companies series, the question is whether contracted earnings and low peer-relative multiples adequately compensate investors for the cost and execution risk of a substantial fleet-renewal programme.
All dollar figures are US dollars. The report is dated 5 November 2026; the $65.45 share price and Cashu-normalised valuation snapshot are from 4 November 2026. Issuer financials run to 30 June 2026. These are dated figures, not live quotes.
The valuation case
- BUY, with a $106.14 model target over a 12-month view. Against the $65.45 reference price, that implies approximately 62.2% upside. The target is a bounded, valuation-anchored reference point, not a probability-weighted forecast.
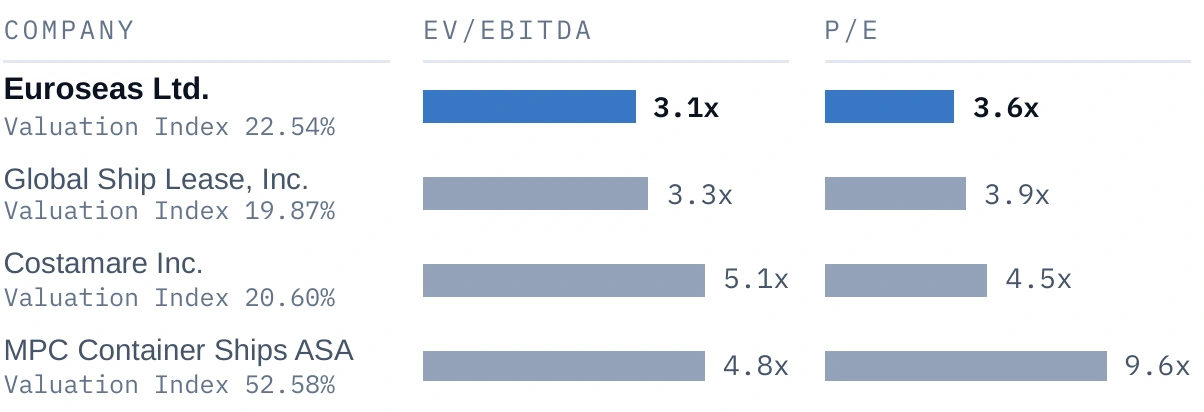
- 3.65× trailing P/E and 3.13× EV/EBITDA. Euroseas trades below Global Ship Lease, Costamare and MPC Container Ships on both measures in the report's peer comparison.
- 22.54% Valuation Index: Undervalued. Lower readings indicate relative cheapness. Global Ship Lease and Costamare also fall in the Undervalued band, so this is partly a sector-wide discount rather than an isolated mispricing.
- 0.89× price/book and 0.30× normalised net debt/EBITDA. Book-value support is modest; low current leverage does not remove the need to finance future vessel commitments.
Charter cover supports earnings visibility
The report describes charter coverage of approximately 100% for 2026 and 91% for 2027. The EM Corfu charter at $62,500 per day and Jonathan P extension at $26,000 per day are expected to contribute about $17.8m and $12.7m of EBITDA, respectively, over their minimum periods. Both commencements depend on scheduled drydocking.
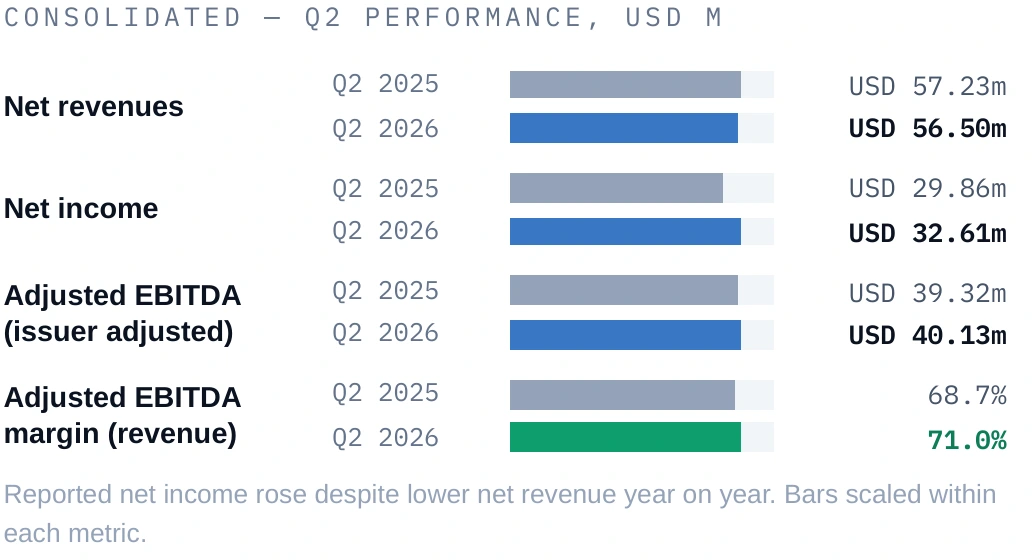
Issuer-adjusted Q2 2026 EBITDA was $40.13m, versus $39.32m a year earlier, even as net revenue fell to $56.50m from $57.23m. Net income increased to $32.61m from $29.86m. Cashu's normalised measures and issuer-adjusted figures use different bases and should not be treated as interchangeable.
What could narrow the discount?
The agreed sale of M/V Evridiki G for approximately $26m is expected to generate a gain of roughly $22.5m, or $3.19 per share. These are expected transaction outcomes in the report, not a claim that completion or the gain has already occurred.
After that sale, the fleet comprises 20 vessels on the water, with 12 newbuildings scheduled from Q3 2027 to Q3 2029. Four intermediate newbuildings already carry charters to 2032–2033 at $32,500 per day. Most deliveries sit beyond the report's 12-month view, so investors should not assume the whole programme will contribute earnings within the target horizon.
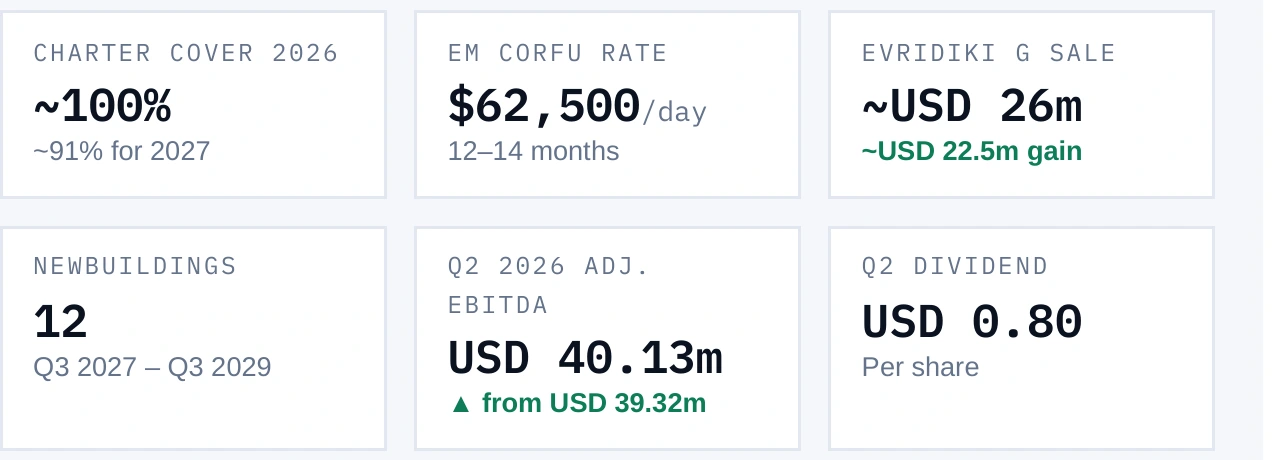
A $0.80 quarterly dividend and repurchases of 480,460 shares to 13 August 2026 support the shareholder-return case, but future distributions are not assured. The 56.41% Sentiment Index is classified as Bullish; it estimates order flow from price and volume, not the identity or intentions of buyers.
The principal risk: funding the newbuilds
Outstanding newbuild commitments were $295.8m at 31 December 2025, including $137.1m due in 2027. Management plans to fund them through own cash and bank debt. Cash and cash equivalents of $157.35m at 30 June 2026 should not be read as surplus cash freely available after all commitments. The report separately quotes $164.3m of restricted and unrestricted cash against $208.1m of outstanding debt.
THE FUNDING TEST
Commitment snapshot at 31 December 2025, as quoted in the report. The 2027 amount is included in the total, not additional to it. Management plans own cash and bank debt; these figures do not establish that financing is secured.
Other risks include drydock costs and delays, shipping cyclicality and EU Emissions Trading System obligations. The fleet faces allowance surrender in 2027 for 100% of covered 2026 emissions; Euroseas seeks charter-party clauses transferring voyage CO₂ costs to charterers, but execution and contract terms matter. Strong charter cover helps near-term visibility, not permanent protection from weaker rates.
How to read the model
The 62.82% Target Index puts Euroseas in the model's “Attractive Target” band. It is an M&A-attractiveness score, not evidence of takeover discussions or an acquisition forecast. The Valuation Index compares a selected peer group and does not establish intrinsic value. A discount can persist if funding, operating performance or sector conditions disappoint.
Sources, methodology and disclosures
This page summarises the supplied three-page Cashu Research Report on Euroseas. Its sources include Cashu-normalised metrics as of 4 November 2026; Euroseas' 2025 Form 20-F; Q2 2026 results released 13 August 2026; the Jonathan P charter extension of 25 August 2026; and the EM Corfu charter and Evridiki G sale announcement of 19 October 2026.
The report discloses AI-assisted narrative synthesis using structured financial data and public-web sources. Fundamentals and peer comparisons draw on licensed S&P Global Market Intelligence data normalised by Cashu. Normalisation does not establish recurring earnings. AI synthesis and underlying data may contain errors or omissions; verify material claims against primary sources.
Confirmed publication disclosure: this report is unpaid and Cashu holds no shares in Euroseas Ltd. The downloadable publication edition carries the same disclosure. No US or Canadian regulatory exemption is asserted. Distribution or use is not intended where contrary to local law. This material does not consider any reader's objectives, financial situation or needs; seek independent professional advice before making an investment decision. Prices and estimates may have changed since the report's snapshot.
Use the download button to access the complete three-page Cashu Research Report, including the original charts, financial comparisons, model glossary and disclosures.
Cover photograph: Pexels. Illustrative containership photograph; not identified as a Euroseas vessel. The three on-page chart panels are reproduced from the supplied Cashu Research Report.