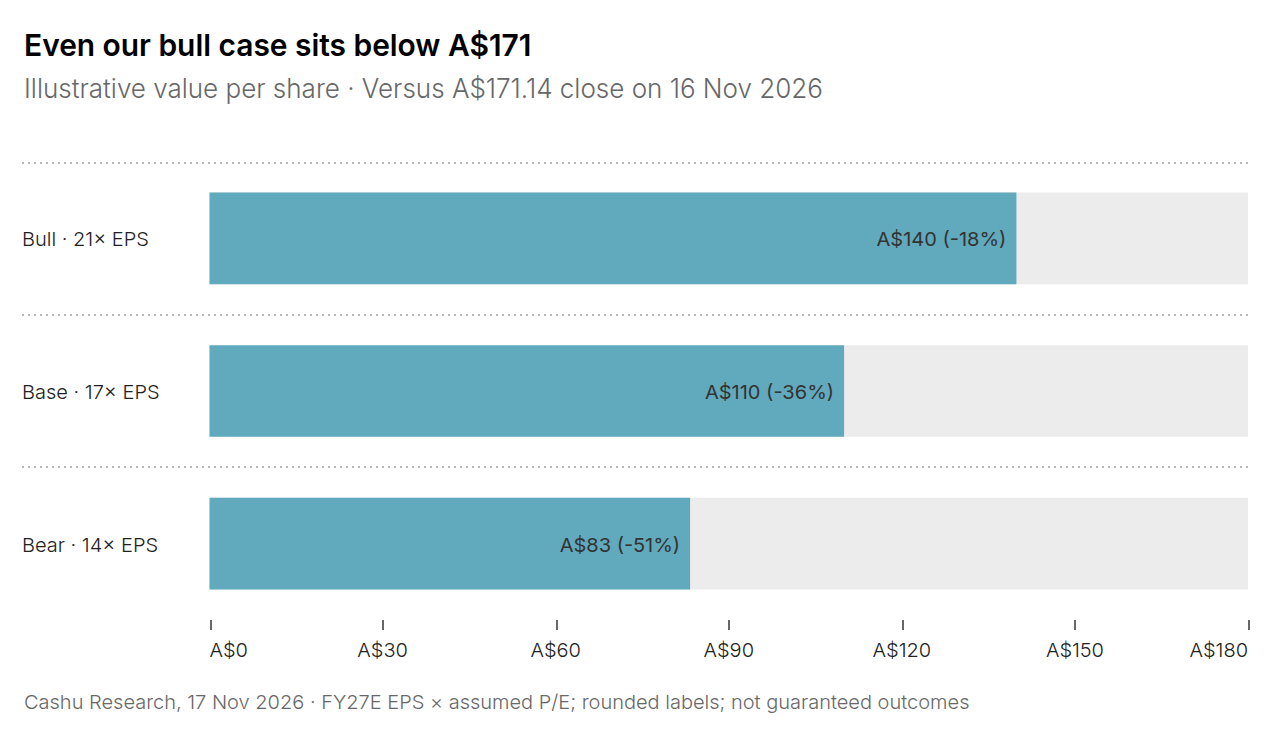
A great franchise can still be a poor investment at the wrong price. That is our call on Commonwealth Bank: SELL, with a 12-month A$110 price target, versus A$171.14 at the 16 November close. The implied downside is about 36%. It is a valuation case, not a prediction of a banking crisis.
Report snapshot: 16 November 2026 close. Growth uses consensus FY27 EPS; targets and scenarios are estimates, not promised returns.
A growth-stock price. A bank's earnings.
Tap any research graphic to view it full size.
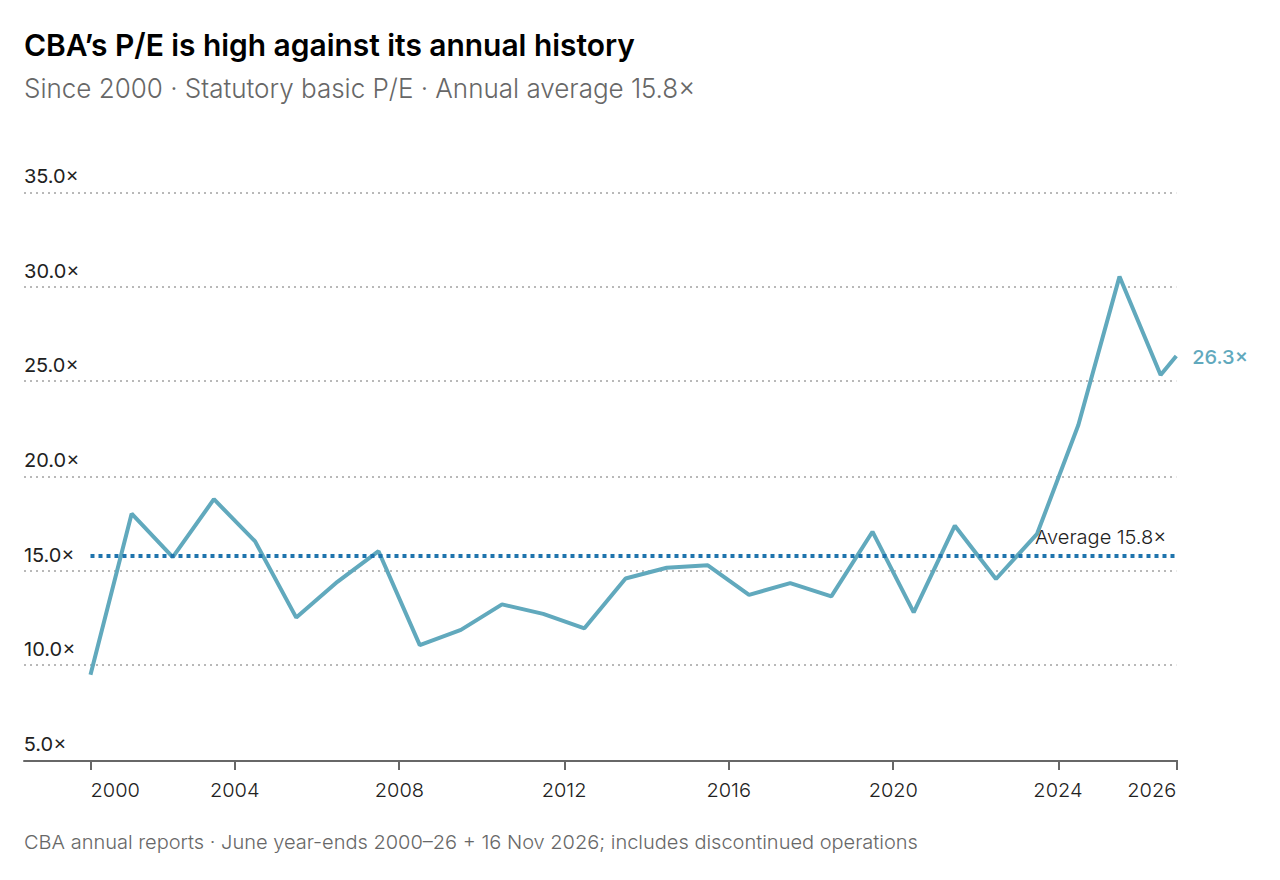
CBA is priced at 25.7 times consensus FY27 earnings. Our report puts its ten-year median near 16.5 times: a premium of roughly 56%. Yet consensus cash EPS rises from A$6.57 to just A$6.66. Investors are paying up for scarcity, index demand and a strong franchise, rather than rapid earnings growth.
The credit cycle is no longer helping
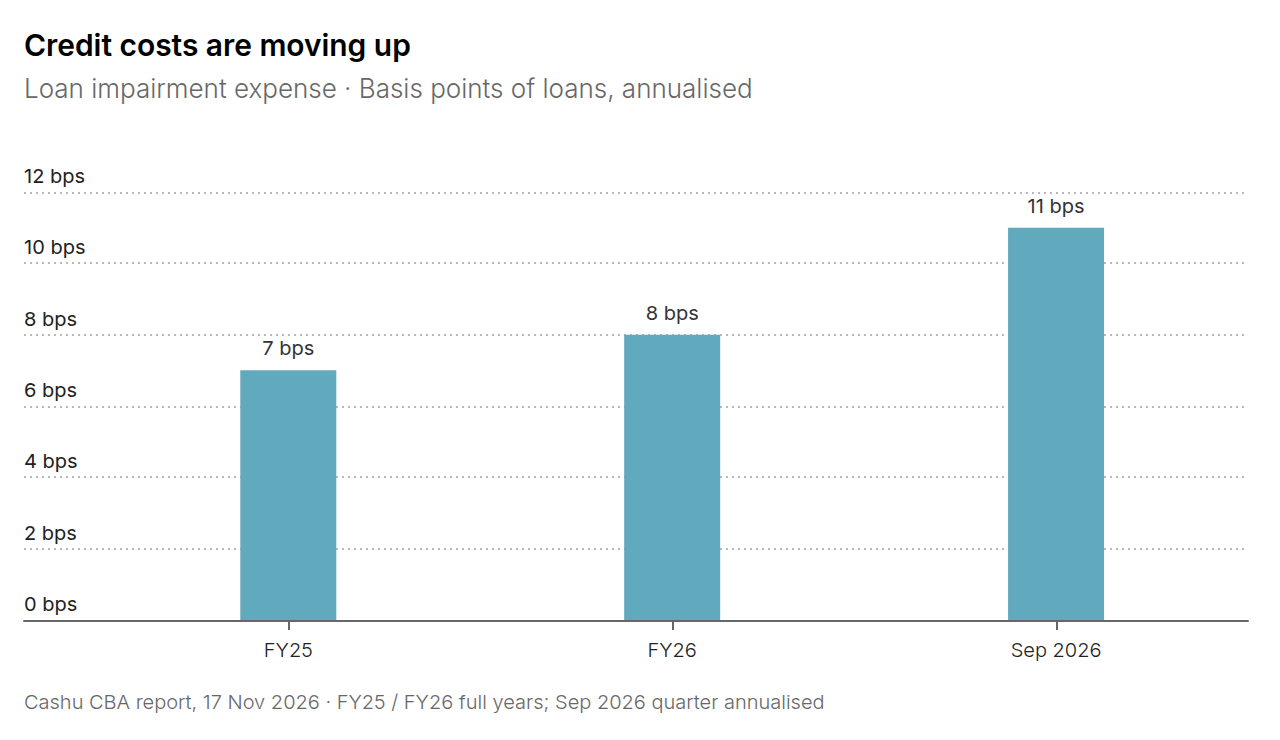
The report's warning comes from CBA's own credit numbers: loan impairment expense rose from 7 basis points of loans in FY25 to 8 in FY26, then 11 annualised in the September quarter. Home-loan arrears reached 0.80%, up from 0.73% in June. Home-loan applications were down 16% year on year.
Housing adds pressure. The report cites national home values 6.7% below their March peak and CBA economists forecasting a 14% peak-to-trough fall. Those are dated observations and a forecast, not a guaranteed path. The risk is ordinary credit normalisation arriving while the shares still carry an extraordinary valuation.
The multiple does most of the damage
Our base case is simple: A$6.47 of FY27 cash EPS × 17 = about A$110. That earnings estimate is only around 3% below consensus. Most of the downside comes from investors paying less for each dollar of profit.
The biggest risk: being early
The biggest risk to our call is being early. Passive flows, franking demand, buybacks and stronger margins could sustain the premium. CBA has defied valuation-led sell calls before.
Our next major test is the February 2027 half-year result: arrears, impairment charges and mortgage growth. A margin beat, contained bad debts or a shallower housing decline would weaken the thesis. Our view: respect the bank. Question the price.
Read the full four-page CBA SELL research report (PDF)
Position and payment disclosure. The supplied report states that Cashu and its directors, employees and associates hold no long or short CBA position, including derivatives; have no commercial relationship with CBA; and received no payment or benefit from any party for this report. These statements relate to this publication, not other companies or articles. Sources, methodology and full disclosuresThis article summarises Cashu Research's CBA SELL note dated 17 November 2026, prepared by Fox Slotemaker. The report's market-price reference is the 16 November 2026 close; its consensus estimates are dated 13 November. Live share-price data is separate from the fixed research snapshot.
Long-run P/E methodology. The historical chart is reconstructed from CBA's annual-report shareholder summaries: unadjusted June closing share price divided by that financial year's statutory basic EPS in Australian dollars, including discontinued operations and abnormal items. It contains every June year-end from 2000 to 2026, plus the 16 November 2026 close of A$171.14 divided by FY26 statutory basic EPS of A$6.499. Later comparative restatements within the cited summaries are used where available; the full history has not been rebased to a single accounting regime. Exceptional gains and losses can materially change statutory EPS, including in 2000. This is an annual-observation series, not daily P/E history, a forward-P/E series or the report's cash-earnings valuation basis.
P/E source tables: 2000 annual report, p. 50; 2005 annual report, p. 48; 2010 annual report, p. 92; 2015 annual report, p. 69; 2020 annual report, p. 286; 2021 annual report, p. 289; 2026 annual report, p. 350.
Sources. FY26 results: CBA Full Year Profit Announcement, 13 Aug 2026. Q1 FY27 trading update, 11 Nov 2026 (CBA ASX announcement): figures as reported by MPA, 11 Nov 2026, ABC News and Morningstar, 13 Nov 2026. Share price: ASX close 16 Nov 2026 via Sharetrader. Consensus target, EPS forecasts and broker ratings: FNArena, 13 Nov 2026. ABS September- quarter lending finance: via ABC News, 11 Nov 2026. Housing: Cotality Home Value Index, October 2026 and CommBank economists, 3 Nov 2026. RBA November decision: TFTC, 2 Nov 2026 and CommBank newsroom. Long-run multiples: GuruFocus, Lonsec and Wilsons Advisory as cited in The Bank Trap. Scenario analysis and price target are Cashu Research's own. Prepared by Fox Slotemaker, Research Manager, Cashu Research.
Position and interest disclosure. At the date of publication, Cashu Group, Cashu Research and their directors, employees and associates hold no long or short position in Commonwealth Bank of Australia securities or in any derivative referencing them, and do not intend to trade in them in the five business days following publication. Cashu has no commercial relationship with Commonwealth Bank of Australia and has received no payment or other benefit from any party for the preparation or distribution of this report. Cashu Group receives fees from other listed companies for research, investor awareness and marketing services; none of those companies is discussed in this report. The analyst's remuneration is not linked to the recommendation or to any trading outcome. This report was prepared from publicly available information as cited; Cashu has not received any material non-public information from Commonwealth Bank of Australia or any other party.
General advice warning. This report has been prepared by Cashu Research, a division of Cashu Technologies Pty Ltd, Corporate Authorised Representative (AR No. 001318029) of Adviser Solutions Group Pty Ltd (AFSL 485946). It contains general information and general financial product advice only and does not take into account the objectives, financial situation or needs of any particular person. Before acting on it, consider its appropriateness to your circumstances and seek independent professional advice. Short selling involves the risk of unlimited loss and is not suitable for most retail investors. Price targets and scenarios are illustrative, rely on assumptions that may not hold, and are not forecasts or guarantees. Past performance is not a reliable indicator of future performance. Figures are as at the dates cited and will have changed.
Rating definitions. BUY (expected return >15% over 12 months); HOLD (−15% to +15%); SELL (<−15%). Business risk Low reflects CBA's franchise, capital and funding; Timing risk High reflects the structural index and super-fund bid described above.